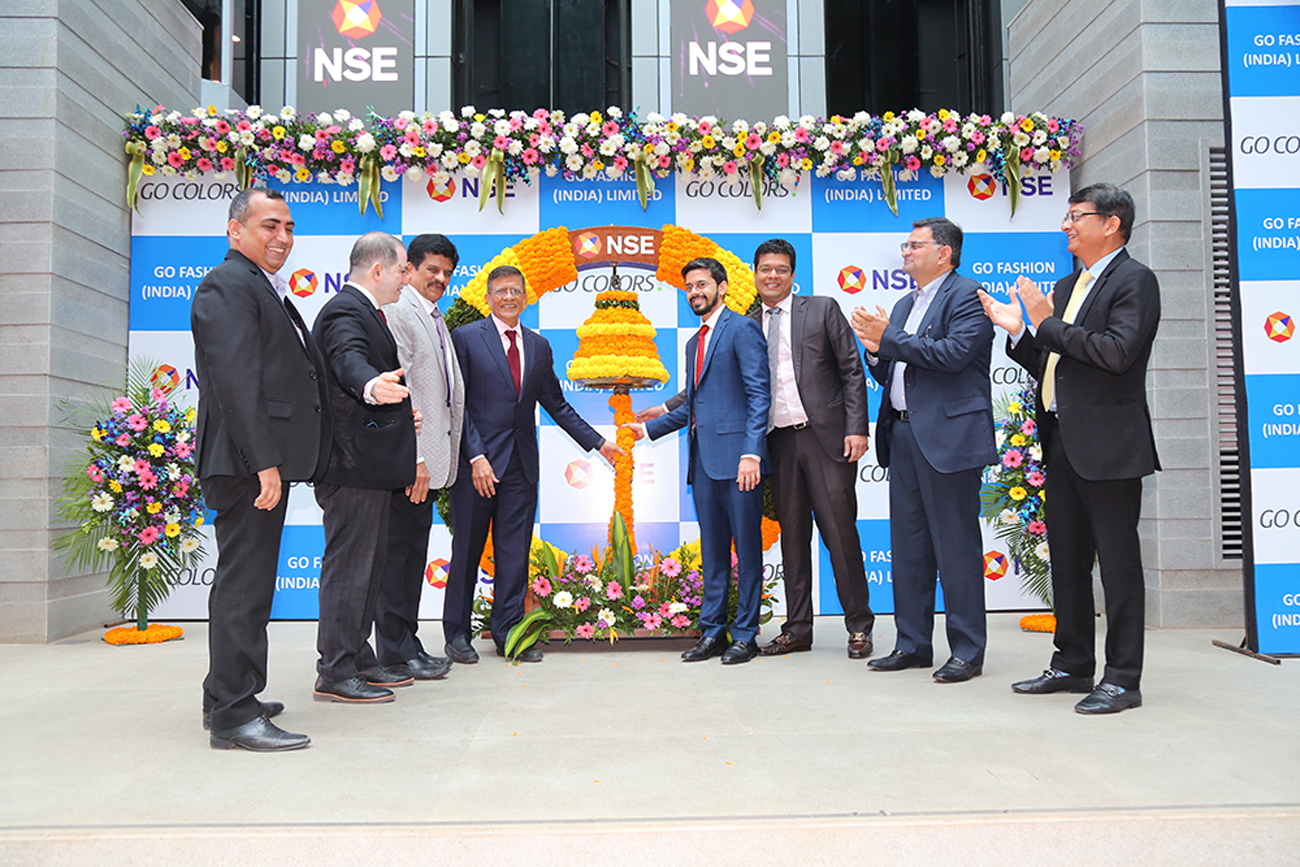
Go Fashion (India) Limited – Share Gains Over 81%

Go Fashion (India) Limited had tapped the capital markets with its fresh issue for Rs 125 crs and an offer for sale of 1,28,78,389 shares listed on the bourses. The discovered price on BSE was Rs 1,316 at which price 1,27,979 shares were traded. On NSE, the discovered price was 1,310 at which price 22,25,709 shares were traded. Approximately 23.52 lac shares were traded at the discovered price on the two exchanges combined.
The QIB portion was subscribed 100.73 times, the HNI portion was subscribed 262.08 times and the Retail portion was subscribed 49.39 times. There were 28.91 lac applications and on basis of lots, the retail portion was subscribed 41.35 times. Overall, the issue was subscribed 135.40 times. The issue for Rs 1,013 crs at the top end of the band raised a subscription of Rs 75,900 crs.

The company allotted 66,10,492 shares at the top end of the price of Rs 690 to anchor investors. These were allotted to 18 anchor investors comprising of 33 entities. The issue had opened on Wednesday the 17th of November and closed on Monday the 22nd of November. The price band was Rs 655-690.

The highest allocation was made to the Government of Singapore who was allotted 8,52,432 equity shares or 12.90% of the anchor allotment. Its associate, the Monetary Authority of Singapore was allotted 1,62,057 shares or 2.45% of the anchor book making a total of 10,14,489 shares or 15.35% of the anchor book. This was followed by Fidelity funds who were allotted 13.16% of the book to three entities. Three domestic funds, namely ICICI, HDFC, and SBI were allotted almost an identical 6.58% of the anchor book. This meant that the top 5 anchor investors were allotted 48.27% of the anchor book.

Domestic mutual funds were allotted 22,04,797 equity shares or 33.35% of the anchor book. This was to 7 mutual funds comprising of 18 schemes.

The high of the day on BSE was Rs 1,341, the low was Rs 1,144.15 and the close was Rs 1,252.60. The gain was Rs 562.60 or 81.54%. On NSE, the high of the day was Rs 1,339.90, the low was Rs 1,143.10 and the close was Rs 1,253.70 a gain of Rs 563.70 or 81.70%.

Exchange Open High Low Close Net Change % Gain/ Loss Wt.Avg Volume Delivery Del %age
BSE 1316.00 1341.00 1144.15 1252.60 562.60 81.54 1255.86 1038817 345783 33.29
NSE 1310.00 1339.30 1143.10 1253.70 563.70 81.70 1255.43 17547917 6877639 39.19
Total 18586734 7223422 38.86

The traded volume on the two exchanges combined was 185.86 lac shares which was 1.27 times the IPO size of 146.90 lac shares and 2.30 times the non-anchor portion of 80.79 lac shares. Delivery volume was 72.23 lac shares which were 38.86% of the traded volume. It was 49.17% of the issue size and 89.40% of the non-anchor portion. The weighted average of the day’s trade was Rs 1,255.86 on BSE and Rs 1,255.43 on NSE.

In terms of institutional or bulk trade, two buy trades were reported on NSE. Both were from Nomura which bought 7.75 lac and 2.25 lac shares at Rs 1,277.97 per share. This means that 12.37% of the non-anchor and 13.84% of the actual delivery had a buyer disclosed.

The issue price of the company was at infinite multiples as the company has reported losses for the year ended March 21 and for the quarter ended June 21. One hopes that there is a turnaround when it reports the next set of numbers whether they are for September or December 2021. As for now, the listing has been excellent and all lucky shareholders who were allotted shares have made money including the leveraged HNI.
Star Health & Allied Insurance Company Limited – Completes Anchor Allocation

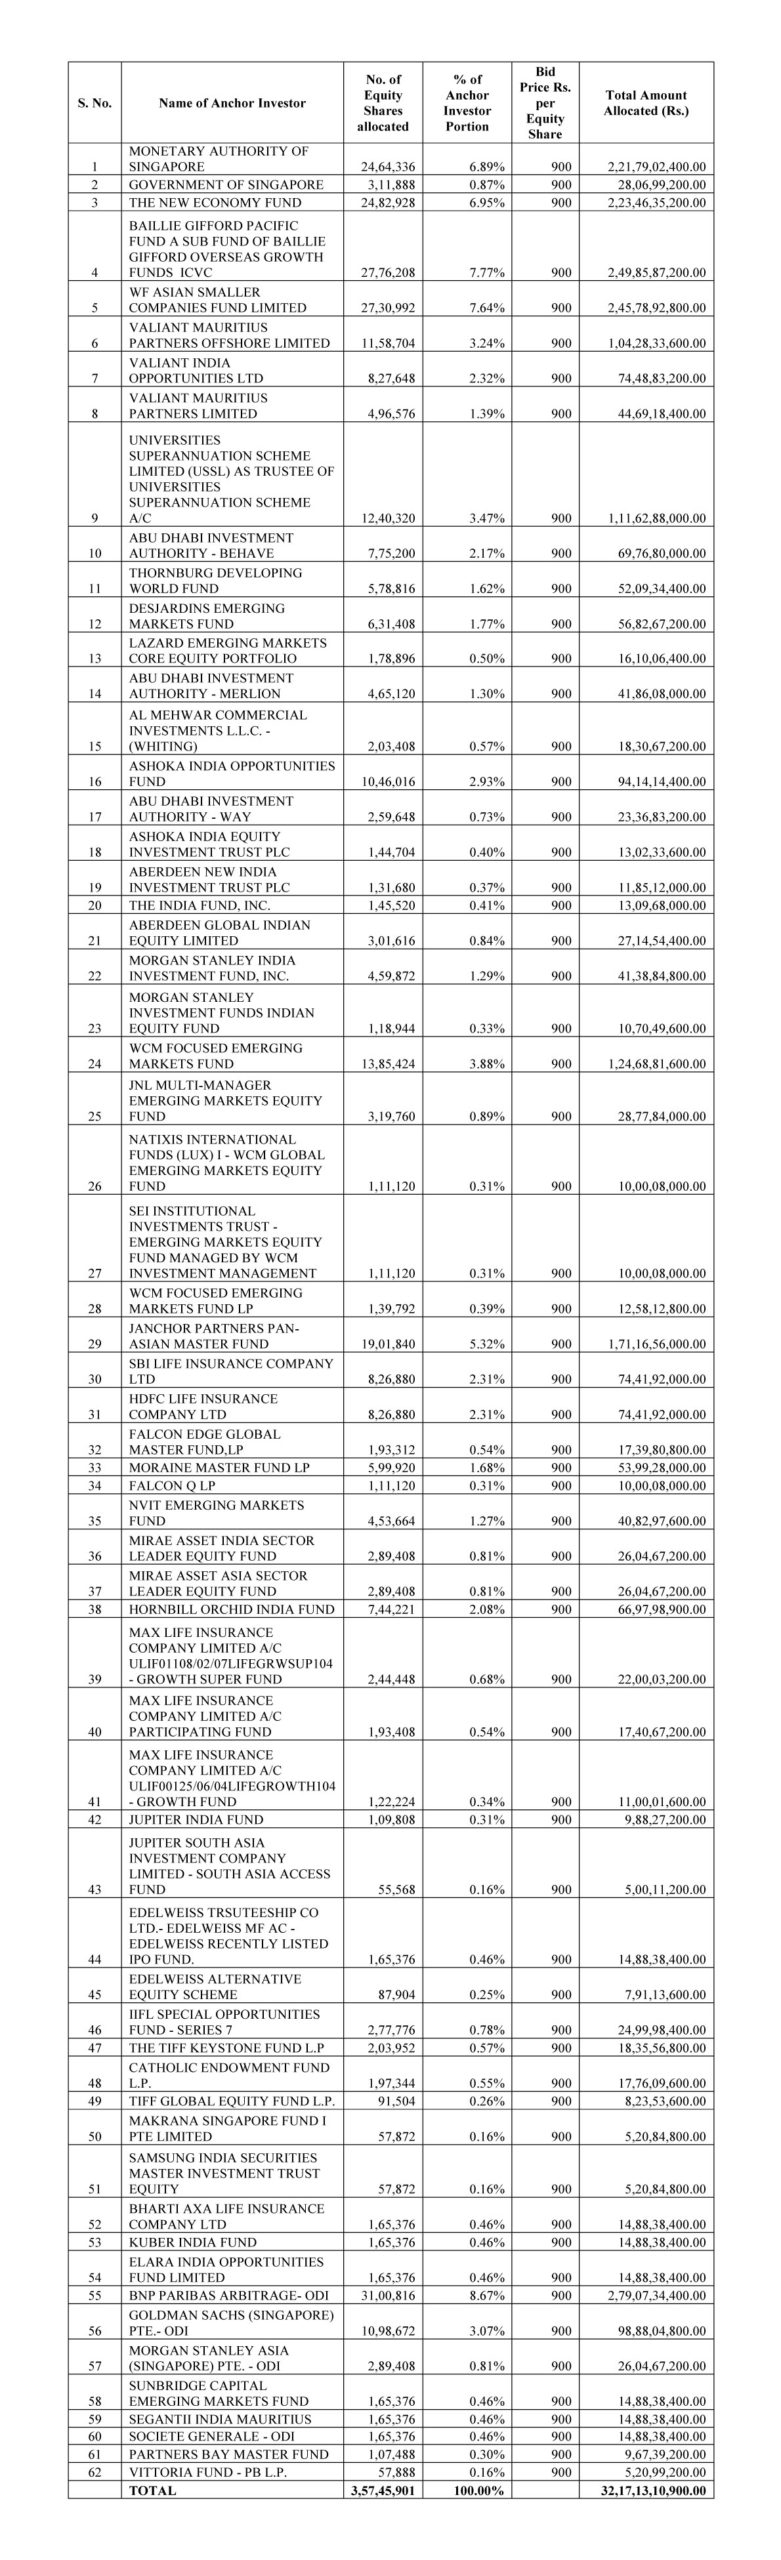
Star Health and Allied Insurance Company Limited which is tapping the capital markets with its fresh issue for Rs 2,000 crs and an offer for sale of 5,83,24,225 shares in a price band of Rs 870-900 completed allocation to anchor investors. The company allotted 3,57,45,901 equity shares to 49 entities comprising 62 entities at the top end of the price band of Rs 900.

The highest allocation was made to Baillie Gifford Pacific Fund who was allotted 27,76,208 shares or 7.77% of the anchor book. This was followed by the Monetary Authority of Singapore and the Government of Singapore who was allotted 6.89% and 0.87% of the anchor book, making a total of 27,76,224 shares or 7.76% of the anchor book. This was followed by the WF Asian Smaller Companies Fund who was allotted 27,30,992 shares or 7.64% of the anchor book. This was followed by Valiant who through three funds was allotted 24,82,928 shares or 6.95% of the anchor book.

The top four anchor investors were allotted 1,07,66,352 shares or 30.12% of the anchor book. The surprising thing was that there was just one domestic fund, Edelweiss Mutual Fund who invested 1,65,376 shares or 0.46% of the anchor book. Very clearly the non-participation by domestic mutual funds whatever be their reason is a disturbing thing as they are the entity that is witnessing the maximum fund flow currently.

The issue would garner Rs 7,249 crs at the top end of the band. The issue has opened on Tuesday the 30th of November and would close on Thursday the 2nd of December.

A full list of anchor investors with their allocation is given below: –

Markets Not Yet Out Of the Woods, Exercise Caution

Markets in the week gone by began on an ominous note with sharp losses on the very first day of the week. They ended the week with even more ominous signs, losing 1.5 times more on Friday than what they lost on Monday, and leaving the world guessing what the new week would unfold for markets globally. BSESENSEX lost 2,528,86 points or 4.24% to close at 57,107.15 points while NIFTY lost 738.35 points or 4.16% to close at 17,026.45 points. The broader markets saw BSE100, BSE200 and BSE500 lose 4.10%, 4.07% and 3.96% respectively. BSEMIDCAP lost 4.14% while BSESMALLCAP was down 2.52%. Markets lost on three of the five trading sessions and gained on two. Interestingly losses and gains were on alternate days.

The Indian Rupee lost 63 paisa or 0.85% to close at Rs 74.87 to the US Dollar. Dow Jones had a torrid half day on Friday when it lost just over 900 points ahead of Thanksgiving weekend in half a day’s trading. For the shortened week, Dow was down 702.64 points or 1.97% to close at 34,899.34 points. At the time of writing this article, Dow Jones futures is down another 185 points.

What has spooked global markets is the new mutant ‘Omicron’ of covid-19 found in Africa. Along with this mutant, there has been a spurt in covid-19 patients in parts of Europe including Austria, Germany and the UK. Cases in the USA have been rising rapidly with even deaths. Many countries including India are looking at new travel restrictions on international flights. In India, the number of vaccinations is increasing and have now touched 122.07 crs which include 78.37 crs first dose and 43.69 crs fully vaccinated. This new variant or mutant would bring an awareness to people and hopefully we should see more people getting vaccinated from hereon.

November futures expired on a week note losing 321 points or 1.80% to close at 17,536.25 points. What is disturbing is the fact that the first day of December series has begun with losses of 509.80 points or 2.91% on NIFTY and 1,687.94 points or 2.87% on BSESENSEX.

The primary market saw the issue from Go Fashion (India) Limited get oversubscribed 135.40 times, with QIB portion subscribed 100.73 times, HNI portion subscribed 262.08 times and Retail portion subscribed 49.39 times. This issue is expected to list on Tuesday in the coming week.

There were two issues which listed in the last week. The first was the issue from Latent View Analytics Limited which has become the most subscribed issue in over a decade with oversubscription of 338.51 times. The issue had garnered subscription of Rs 1.13 lac crs against an issue size of Rs 600 crs. The share which was issued at Rs 197 ended day one at Rs 488.60, gaining 148%. By the end of the week the share had gained further and closed at Rs 695.95 a gain of 253.27%.

The second share to list was Tarsons Products Limited which had issued shares at Rs 662. After a sedate discovered price of Rs 700, the share hit the upper circuit and closed at Rs 840, a gain of 26.89%. In what could be an interesting point to ponder upon, of the 22 shares that have listed from the 16th of August, as many as 10 or 45.45% are trading below the issue price. This clearly shows the fact that pricing of issues by merchant bankers, private equity investors and promoters is taking their toll on the markets.

The first issue to open next week is Star Heath and Allied Insurance Company Limited which is tapping the capital markets with its fresh issue for Rs 2,000 crs and an offer for sale of 5.83 cr shares in a price band of Rs 870-900. The issue would garner Rs 7,249 crs at the top end of the band. The issue opens on Tuesday the 30th of November and closes on Thursday the 2nd of December. The company which is into health insurance is the largest private sector player, but reported losses for the year ended March 2021 and the half year ended September 2021 as well. The company in the current year would be unable to turn back into profits because of the claims made on account of covid-19. Further the claims on account of other diseases which are seasonal and viral in nature like dengue, chikungunya and malaria will cause a hole in the balance sheet of star health. I believe the company at the current rate may not make profits even in FY 23. The PE for the stock is infinite and even the NAV as on 30th September is Rs 57.83. The issue is expensive and investors should spend the Rs 14,400 that they would have applied in the share to buy health insurance for covid-19 and the other diseases. This would be far for rewarding as health would be protected, and health is wealth.

The second issue is from Tega Industries Limited which is tapping the capital markets with its offer for sale of 1,36,69,478 shares in a price band of Rs 443-453. The issue would garner 619 crs at the top end of the band. The issue opens on Wednesday the 1st of December and closes on Friday the 3rd of December. The company is in the business of manufacturing recurring consumable products used in the mining industry and is a sizable player in this field. The company has three plants in India and three abroad in Australia, Chile and South Africa. The company reported an EPS of Rs 20.48 on a fully diluted basis for the year ended March 2021. The PE multiple for the company at this EPS is 21.63-22.12. The nearest comparable for the company is a player known as AIA Engineering who makes similar equipment used by cement plants while Tega does this for the metals mining industry. The private equity investor Wagner is exiting the company after 10 years and would be making a return of 2.62 times. Considering the returns that one is seeing private equity players make and the way fortunes of the mining industry have changed, one believes the returns are sub-optimal. Take a measured call on investing in the company.

Coming to the week ahead, markets would be choppy, volatile and more importantly, circumspect. While FII’s have been selling aggressively in the secondary market, the spate of IPO’s seems to be never ending. Markets need to stabilise and get over the fear of valuations, covid-19 new strain, FED interest rates likely to increase and a host of smaller issues before sanity returns. The fact that we saw oil prices fall close to 10% is also not good for the present state of global markets.

It makes sense to keep cash on hand and indulge in some bargain hunting from the large cap stocks only. Use any rallies which happen which may be classified as corrective or dead cat bounce to sell into and book profits. However, refrain from shorting as the current badly mauled bull would look to retaliate. Allow the markets to consolidate and find new levels of stability before making new commitments.

Subscribe to RSS Feed Follow me on Twitter!