Route Mobile Limited Lists With Gains Of 86%

Shares of Route Mobile Limited listed on the bourses and had a dream debut. The company had tapped the capital markets with its fresh issue of Rs 240 crs and an offer for sale of Rs 360 crs. The price band of the issue was Rs 345-350. The issue had opened on Wednesday the 9th of September and closed on Friday the 11th of September. Shares which were issued at Rs 350, debuted at Rs 708 on BSE and Rs 717 on NSE. They closed at Rs 651.10 and Rs 651.30 respectively. The issue was subscribed a massive 74.36 times overall with QIB portion subscribed 91.06 times, 195.61 times, Retail 12.85 times. There were 15.16 lac applications.
The company allotted 51,42,856 equity shares to 15 investors comprising of 23 entities. The highest allotment of 3,94,890 shares or 7.68% of the anchor portion was made to 6 investors or entities. These comprised names such as Franklin, Goldman Sachs, SBI Life Insurance, Kuwait Investment Authority, Vantage Equity Fund and Axis Mutual Fund.

Shares in price discovery opened at Rs 708 on BSE and Rs 717 on NSE. The high which was made immediately on opening was Rs 735 on both exchanges. The low was also an identical Rs 625 on both exchanges. The close Rs 651.10, a gain of Rs 301.10, or 86.03% on BSE and Rs 651.30 on NSE, a gain of Rs 301.30 or 86.09% on NSE. The traded volume was 27.26 lacs on BSE and 291.89 lacs on NSE. The combined volume was 319.16 lac shares which was 1.86 times the issue size and 2.60 times the non-anchor issue size. Weighted average of the day’s trade was Rs 684.95 on BSE and Rs 686.06 on NSE. Seeing the difference in closing price which is lower than the average, indicates that the share was under pressure and the sharp fall from the high to the low which happened quite quickly caused this pressure. Deliveries were 117.28 lacs which was 36.75% of the traded volume. It was 68.42% of the issue size and a massive 97.74% of the non-anchor portion.

Exchange Open High Low Close Net Change % Gain/ Loss Wt.Avg Volume Delivery Del %age
BSE 708.00 735.00 625.00 651.10 301.10 86.03 684.95 2726932 817676/td>

29.99
NSE 717.00 735.00 625.00 651.30 301.30 86.09 686.06 29189660 10910628 37.38
Total 31916592 11728304 36.75

On the institutional front, Goldman Sachs bought 24,09,343 shares at Rs 705.95 on NSE in four different accounts while Kuwait Investment Authority bought 5,78,504 shares at Rs 697.25. With almost a fourth of the shares bought by institutional investors, the story of Route Mobile is not over on listing day.

There seems to be anew trend emerging on performance of shares on listing day. The gains on listing day are in the region of 70-100% and delivery in excess of 92%. This trend began with the very first listing after the pandemic began and saw Rossari Biotech gain over 74% and deliveries of 92.68% of the non-anchor portion.

In the case of Happiest Mind, the gains were 123% and deliveries were 92.99%. Here in the case of Route Mobile, the gains were 86% and deliveries were 97.74%. It appears the street’s expectation from primary market has changed or is changing. The belief is that issues would get heavily oversubscribed and that HNI’s would push up the cost of the issue on account of interest on their leveraging. This would ensure that there is a health grey market premium for the same and then all successful applicants whether they be QIB, HNI or Retail would make a killing and exit lock, stock and barrel on day one. The new entrants into the company who bought these shares would believe that this is the best opportunity and there is more upside as the share performs.

As long as everybody is happy, who am I to have any complaints.
Action To Shift To Spate Of New Issues

The week gone by had plenty of action and was volatile. While the benchmark indices were just about flat, BSEHEALTHCARE and BSEIT gained significant ground and helped the benchmark indices. Similarly post the SEBI announcement on multi-cap funds being directed to match the allocation of stocks based on their definition of large cap, midcap and Smallcap at 25% each as a threshold level, we saw BSEMIDCAP and BSESMALLCAP indices gain substantially.

BSESESEX lost 8.73 points or 0.02% to close at 38,845.82 points while NIFTY gained 40.50 points or 0.35% to close at 11,504.95 points. The broader market saw BSE100, BSE200 and BSE500 gain 0.67%, 0.92% and 1.22% respectively. BSEMIDCAP gained 2.65% while BSESMALLCAP was up 5.09%. Clearly market breadth gained while the benchmark indices were flat. BSEHEALTHCARE had a huge gain of 9.14% lead by Dr Reddy which was up 21.04% and supported by Lupin 12.31% and Cipla 11.16%. Even BSEIT gained 6.19%. The laggard was BSEBANKEX which was down 1.84% with the banking pack losing for the third consecutive week. SBI was down 4.98% for the week.

The Indian Rupee gained Rs 0.10 or 0.14% to close at Rs 73.44. Dow Jones too ended flat for the week losing 8.22 points or 0.03% to close at 27,657.42 points.

From the above movement one can infer that there is some fatigue factor setting in among the benchmark indices stocks. The rally which was earlier led buy one single stock Reliance has now shifted to a handful of pharma and IT stocks. With their weightage being significantly lower, the net effect is not here to be seen. The gains are offset by losses in the BFSI space. In the broader markets there is a wider participation in small and midcap stocks and people seem to be mis-reading the SEBI circular. How long this optimism remains is anybody’s guess.

There is plenty of action in the primary markets. Shares of Happiest Mind Technologies listed on Thursday and had a dream debut with the stock price gaining a massive 123.49% to close at Rs 371, against the issue price of Rs 166. Considering the non-anchor portion which has a lock-in of 30 days, delivery on day one was to the extent of 92.99% of the IPO size. This indicates that almost all except 7% of the investors whether they be QIB, HNI or Retail sold on day one. The share closed at Rs 358.45 for the week, a gain of 115.93%. Effectively we have new investors in Happiest Mind who have invested at Rs 370 instead of Rs 166.

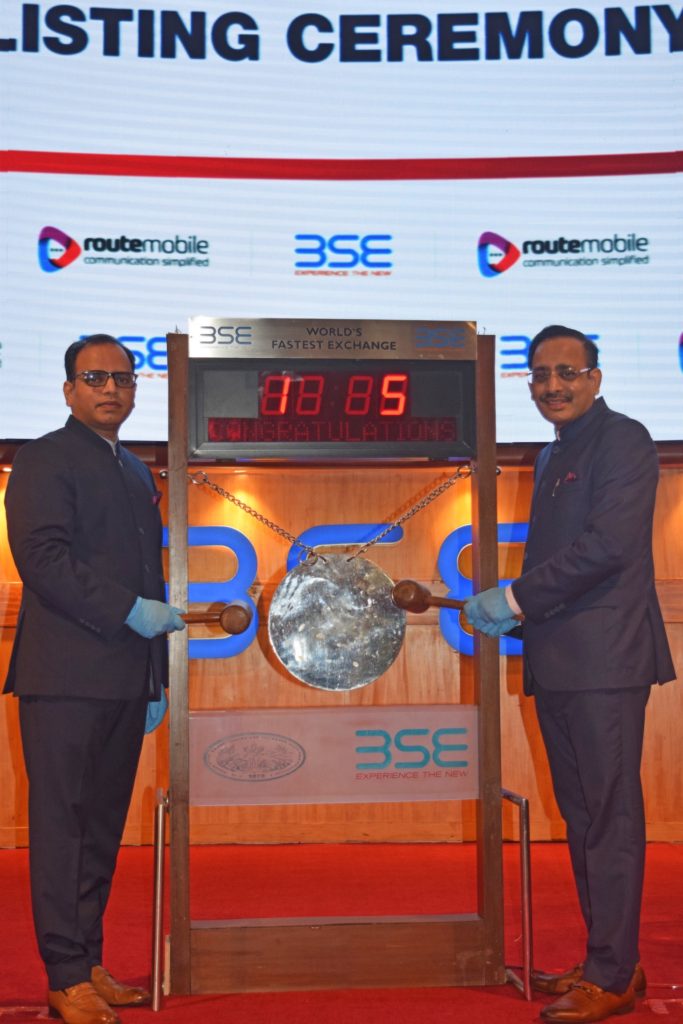
Shares of Route Mobile Limited would list on Monday the 21st of September.

The week ahead sees two primary market issues open on Monday and one open on Tuesday, making a total of three issues for the week. It seems September has suddenly brought the primary markets alive and there is a strong possibility that the last week of September may see a couple of more issues opening.

The first issue opening on Monday the 21st of September and closing on Wednesday the 23rd of September is from Computer Age Management Services Limited (better known as CAMS). The issue is an offer for sale from NSE Investment for 1.82 cr shares in a price band of Rs 1229-1230. The company’s primary business is being an RTA (Registrar and Transfer Agent) for mutual funds. The EPS for the year ended March 2020 is Rs 35.54 and the price earning multiple at which shares are being issued is 34.58-34.61. The asking price is rich in valuation and may not offer much scope for appreciation after listing. The expected listing price is likely to be in the region of Rs 1560-1600.

The second issue is from Chemcon Speciality Chemicals Limited which is into the business of speciality chemicals in the pharmaceutical and completion fluids for the oil well industry. One of the raw materials for the company is the bromide family which is a hazardous chemical and a difficult material and chemistry to handle. One of the recently listed peers in the similar field in Neogen Chemicals which also processes Bromide for different application. The issue opens on Monday the 21st of September and closes on Wednesday the 23rd of September. The price band is Rs 338-340. The EPS for the year ended March 2020 is Rs 15.37 and the PE multiple is between 21.99-22.12 times. The issue consists of a fresh issue of Rs 165 crs and an offer for sale of 45 lac shares.

The third and final issue for the week is from Angel Broking Limited which opens on Tuesday the 22nd of September and closes on Thursday the 24th of September. The company is issuing fresh shares for Rs 300 crs and an offer for sale of Rs 300 crs. The price band is Rs 305-306. The EPS for the year ended March 2020 is Rs 11.44. The PE multiple for the company based on this EPS for March 2020 is 26.66-26.75 times. Even considering the fact that the April-June quarter was a great period for the broking industry during the covid-19 pandemic time, it is difficult to expect the good times to continue. Margin rules being changed have affected volumes at the bourses and volumes have slipped from peak levels. Secondly while the company had garnered new clients with a massive drop and restructuring of broking rates, the newness and effectiveness of the growth on account of the same is wearing off. At the asking PE, the share is more expensive than listed players from the industry, challenging the logic to subscribe.

The week ahead sees September futures expire on Thursday the 24th of September. The current level of NIFTY of 11,504.95 points means that the series is lower by 54.30 points or 0.47%. While the loss is marginal, the law of averages may play catch up as we have been seeing monthly gains for the last three months from June 20 expiry onwards.

Covid-19 front saw the world have 312,30,588 patients, 965,065 deaths and 228,33,523 people recover. In India the number of patients has increased to 54,87,580 patients, 87,909 deaths and 43,96,399 people having recovered. Compared to the previous week the world saw 20,49,683 new patients, 36,800 deaths and 18,06,747 people recovering. In India the number of new patients has increased by 6,42,577 people, 8,155 deaths and 6,19,355 people recovering.

The week ahead would see the focus shifting to the primary markets with three new issues and one new listing. Further the euphoria in the small and midcap space would in all probability reduce and people take a breather. Also, the huge rally in HealthCare and IT stocks could also see profit taking while BFSI space is likely to see some value buying. Considering all of these factors including September futures expiry, expect markets to be choppy, volatile, two sided sharp movements and mixed. Trend determination may be difficult in the week and one must be prepared to see a correction which is long overdue. Caution is drawn to people asking them to refrain from shorting the market on an overnight basis and use sharp rallies to sell and equally sharp dips to buy. Be patient.

Cams IPO review link – https://youtu.be/TELR7ViTfQg

Chemcon IPO review link – https://youtu.be/EhXkSQlW1IE

Chemcon Speciality Chemicals Limited – Completes Anchor Allocation

Chemcon specialty Chemicals which is tapping the capital markets with its fresh issue for 165 crs and an offer for sale of 45 lac shares completed allocation to anchor investors. The company allotted 28,05,880 equity shares to 13 Anchor investors comprising of 16 entities. The highest allocation was made to ICICI Prudential and IDFC emerging Business Fund and Dynamic Equity Fund who were allotted 3,08,836 shares or 11.01% of the anchor allocation.

The issue opens on Monday the 21st of September and closes on Wednesday the 23rd of September. The price band is Rs 338 to Rs 340. Looking at the recent success of issues from Happiest Mind, Rossari Biotech and the yet to be listed Route Mobile, this issue too would receive excellent response. One may also compare it with Neogen Chemicals, which is into the business of processing Bromine which is a difficult and hazardous chemical like Chemcon.

The full list of anchor investors with their allotment is given below: –

Subscribe to RSS Feed Follow me on Twitter!