
Brooks Laboratories IPO: Does not assure capital safety.


Valuations offer no scope for appreciation

Brooks Laboratories is tapping the capital markets with its IPO which has opened on Tuesday the 16th of August and closes today the 18th of August. The company is raising Rs 63 crs in a price band of Rs 90-100.

Price Band Rs 90 – Rs 100
Issue Size in Rupees Rs 6300 lacs
Issue Size in Shares 70,00,000 Equity Shares at Rs 90 to 63,00,000 Equity Shares at Rs 100
QIB’s 35,00,00 Equity Shares at Rs 90 to 31,50,000 Equity Shares at Rs 100
Non Institutional Investors 10,50,000 Equity Shares at Rs 90 to 9,45,000 Equity Shares at Rs 100
Retail Investors 24,50,000 Equity Shares at Rs 90 to 22,05,000 Equity Shares at Rs 100
Book Running Lead Manager D & A Financial Services Private Limited
Isssue Opening Date Tuesday 16th August
Isssue  closing date Thursday 18th August
IPO Grade ICRA grade 2/5 indicating below average fundamentals
Paid -up Capital Pre IPO 98,86,422 Equity Shares
Paid -up Capital Post IPO 1,68,86,422 Equity Shares at Rs 90 to 1,61,86,422 Equity Shares at Rs 100
Market Cap post listing Rs 15197 lacs at lower band to Rs 16186  lacs at higher band
Bid Lot 60 shares
Bidding Amount for Retail 1980 shares at Rs 100 or Rs 1,98,000 per application

Business

The company is in the business of manufacturing injections, dry tablets and dry s company is in the business of manufacturing injections, dry tablets and dry syrups in the state of Himachal Pradesh at Baddi. The company has an installed capacity of 300 lac injections, 1200 lac tablets and 120 lac numbers of dry syrup. The present product portfolio comprises of 28 injectable, 19 tablets and 2 dry syrups which are marketed domestically. The company also manufactures for companies like ZydusCadila, Aristo Pharma, FDC, NectarLifesciences amongst others. Baddi has 100% excise exemption for the first 10 years and a tax break of 100% for the first five years and then 30% for the next five years.

Objects of the issue

The objects of the issue are as follows: –

1. To set up new manufacturing unit at JB SEZ Pvt Ltd for manufacturing pharmaceutical formulations
2. To meet long term working capital requirements
3. To meet general corporate purposes.
4. To meet issue expenses and listing of shares on stock exchanges.

Financials

The turnover of the company has increased from Rs 4383.15 lacs in March 2009 to Rs 4545.35 lacs in March 2010 and Rs 5319.92 lacs in March 2011. The net profit has however jumped from 296.07 lacs in March 2009, to Rs 519.62 lacs in March 2010 and Rs 688.79 lacs in March 2011. The net margins have almost doubled from 6.75% in March 2009 to 12.95% in March 2011. This jump in margins seemsunexplainable and unjustified. A job work and small scale marketer of products does not enjoy such margins.

year 2009 year 2010 year 2011
Income
Of Products Manufactured by the issuer 4492.6 4506.9 5253.9
Of Products traded by the issuer 0 0 0
Total revenue 4492.60 4506.90 5253.90
Other Income/job work 4.15 14.51 24.01
increase/decrease in stock -113.60 23.94 42.01
Total Income 4383.15 4545.35 5319.92
Raw materials consumed/Purchases 3354.80 3309.80 3746.50
Other expenses 708.20 688.40 843.80
Total Expenses 4063.00 3998.20 4590.30
Profit before tax 320.15 547.15 729.62
Provision for tax 24.08 27.53 40.83
Profit After Tax 296.07 519.62 688.79
NET MARGINS 6.75 11.43 12.95

Comparison

The company has chosen to compare itself with two companies namely Amrutanjan Health Care and Bafna Pharmaceuticals Ltd. Amrutanjan is into a niche product namely manufacturing pain balms and has a very low equity base of just 3.03 crs or 30 lac equity shares. BafnaPharma is now in the process of expanding its manufacturing activities after getting the necessary regulatory approvals in UK to enter the European markets and also markets in Africa.

Brooks Laboratories earned Rs 519.62 lacs in March 2010 which means an EPS of Rs 5.25 on the old capital of Rs 98.86 lac shares or Rs 988.64 lacs. The EPS for the year ended March 2011 would improve to Rs 6.96 on the basis of historical capital.

Merchant banker’s track record

The last issue brought to the capital markets by the merchant banker D & A Financial Services Pvt Ltd was ShilpiTechnocables Limited. The company had issued shares in a price band of Rs 65-69 and the shares listed on the 8th of April. The price chart below shows how the shares have fallen to a dismal level of Rs 13 as of yesterday.

Valuations

The company is offering its shares at a PE multiple of 22.06 times at the lower end of the price band of Rs 90 and at 23.53 times at the upper end of the price band. This is yet another company who has chosen not to meet members of the investing community or people from the media in connection with its IPO. Very clearly this and the size of the issue, steep valuations and the current state of the market make me fairly worried about the prospects of the company going forward.

Conclusion

They say in the English language “when in doubt stay away” and I believe this would be the best thing to do in this issue. At the time of writing this article there is not even a single bid from QIB’s.

SEBI Disclaimer: – I do not intend to subscribe to the above issue.
Key Takeaways from the Markets

The present markets have become extremely volatile and weak. We seem to have lost our mind and continue to blindly follow overseas cues. These are some observations on some interesting and key takeaways from the market in the present scenario.

IPO’s don’t seem to be doing too well and suddenly we find that the new buzz word is bond issues. The same grey market instruments like “koshtak” where the whole form is bought and the premium per bond instead of shares are being quoted. Some intermediaries are selling bond issues like equity issues and talking about listing gains. These bond issues are keeping many investment banks and broking houses busy and with one bond issue every week currently happening, no one is really complaining.

The recent IPO’s in the equity market have been a complete mixed bag. The last issue which closed on Friday was from Tree House Education. The company tried to play safe and fixed a price band as big as Rs 132-153, with an objective to take advantage if the markets improved. They also offered a discount of Rs 6 per share to retail investors. Unfortunately markets were bad and the Anchor book was also subscribed at the lower end of the price band at Rs 132. The overall subscription levels were not too encouraging and the issue just aboutmanaged to pull through.

Friday saw the listing of L&T Finance Holdings Limited. This company also had tried to take advantage and kept a big price band. The pre-IPO allotment done by the company was at Rs 55 and the price band was this price, plus minus Rs 4 on either side making it Rs 51-59. The anchor book was done at a 0ne rupee premium to the pre-IPO price at Rs 56. However QIB’s let the issue down and the issue had to be priced at Rs 52. The HNI portion saw withdrawals which were more than half the total book and the overall HNI book which closed for subscription at 6.15 times was reduced to 5.94 when final bids were in and became even less than half when allotment was made at 2.94 times. Withdrawals are a phenomenon which happens in every issue depending on the market condition and likely allotment and listing price. It does not only happen in the case of IPO’s like Vaswani Industries.

We then recently had an issue from Inventure Growth which is a stock broking firm. The company issued shares at a price of Rs 117 at which price the PE multiple based on fully diluted, post issue capital based on March 11 numbers would be a staggering just about 40 times. What is noteworthy is the broking business in general is not doing well and this company in particular had only in the previous year chosen to close down its arbitrage business which was the biggest income generator. The company chose the other route of over pricing the issue and then using “friendly intermediaries” who were given other forms of incentives to sell the issue. The issue was subscribed, had a very explosive start on listing day and is now trading at PE multiples of close to 70 times. It may be noted that well established broking houses like MotilalOswal and Edeleweiss are trading at multiples of just about 10 or roughly 1/7th of Inventure.

To add insult to injury this company chose not to have even a road show for its IPO but chose to have a listing ceremony for the company.

Yet another company which did the same was Shilpi Cable Technologies Limited which issued shares at Rs 72. This company and its merchant banker chose not to market the issue and decided not to have a road show but again had a grand listing ceremony. I believe the entire process of an IPO which invites an interaction between the issuer company and the likely investing public is being twisted and put into a different shape. There is an issue opening ad, the issue opens with valuations which cannot be comprehended, the issue manages to get subscribed and lists. On listing it bombs either on the first day itself as Shilpi Cables or a couple of days later like Timbor Home. The end is fixed and pre-determined or as people may say fait-accompli.

Tuesday sees yet another issue opening in the form of Brook’s Laboratories. The company is seeking to raise Rs 63 crs in a price band of Rs 90-100. Not much is known about the company except that the merchant banker is common as in the case of ShilpiTechnocables. This company has also not chosen to have any roadshow and like in all such companies is extremely overpriced.

In terms of bond issues last we saw the successful issue from Shriram City Union and this week will see the issue from Mannapuram. Mannapuram is offering bonds with two maturities of 400 days and 2 years. The 400 day issue becomes an attractive investment from tax purposes as no interest would be paid during the life of the bond and would accrue on the instrument to be paid on maturity. This could be used as a capital gains instrument and become effectively tax free if held to maturity.

The following week Muthoot the loan against gold company would be launching its bond issue.

I believe the time has come where promoters and merchant bankers need to introspect about the state of the market and about valuations at which offerings are to be brought to the market place. If the quality of issues at fair valuations does not happen, the proliferation of “MANAGED” issues will grow very rapidly as is currently happening and will kill the interest in the primary markets completely. I believe this is not in the interest of primary markets which are a catalyst to raising capital, the merchant banking community and the promoters looking to tap the capital markets. With SEBI planning to introduce track record of merchant bankers bringing issues, it would only be a matter of time before people realise the good from the bad and make life difficult for the “managed” issues.

We have just celebrated our 64th Independence Day and the need of the hour as is being seen and felt all over the country is to weed out corruption and bring better governance. Let us hope when we celebrate the 65th Independence Day one year from now, the capital market intermediaries and community is able to hold their heads high and say that we have done our bit for better governance and reducing corruption if not eliminating it.

Jai Hind!

L&T Finance Holdings: Listing leaves a lot to be desired


Share trades at a discount of almost 4%, closes below Rs 50

Shares of L&T Finance Holdings Limited listed on Friday the 12th of August amidst a lot of fanfare at the NSE. This was an issue from the L&T group after 61 years and the loyal investor base built up by the company reposed its faith in the group. The issue was subscribed an overall 5.34 times led by huge support from retail which saw their category being subscribed 9.61 times.

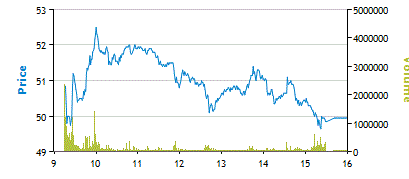
Coming to the listing itself the share listed at Rs 51 on the BSE and Rs 53.85 on the NSE. The high was Rs 52.50 on the BSE and the open of Rs 53.85 on the NSE. The high was made on the BSE at around 10 am in the morning and the low of the day was made around 3.15 pm all almost at the end of the day’s trade, signifying the continued selling pressure on the stock as it traded. This does not augur well for the stock in the coming days and indicates that there could be further pressure as the days pass.

Exchange Open High Low Close Net Change % Gain/loss Wt. Avg Volume Delivery Del %age
BSE 51.00 52.50 49.50 49.95 -2.05 -3.94 50.90 44347679 11078125 24.98
NSE 53.85 53.85 49.30 50.05 -1.95 -3.75 50.91 98188151 26715996 27.21
Total 142535830 37794121 26.52

Looking at the table above one finds that the total traded volume 1425.35 lakh shares against the IPO size of 2339.56 lakh shares which means 61% of the IPO was traded on day one. The total delivery volume was 377.94 lakh shares or 26,52% of the total traded volume and 16.15% of the IPO size. The weighted average volume of the shares traded was Rs 50.90 on the BSE and Rs 50.91 on the NSE respectively. This weighted average is almost one rupee higher than the weighted close of the day. This is yet another issue which has excellent fundamentals, was highly priced as the price band of Rs 51-59 indicated. The management of the company should be appreciated that they were responsive to the needs of the time and chose to price the issue at Rs 52 even after the issue had a benchmark price of Rs 55 as a pre-IPO price. There was a further validation of the price when the anchor investors came in at Rs 56. The retail book was oversubscribed 9.61 times which means that almost 62% of the total book was subscribed by retail investors.

I believe having realised the strength of this loyal base that the company had, it chose to effectively give a discount and price the issue at Rs 52 and ensure that retail investors did not suffer. This category is the backbone of support for any company.

Looking at the price chart one can see that the share after opening at a discount to the issue price of Rs 52 and trading at Rs 51, rose to touch the day’s high of Rs 52.50 and had done this in the first hour of trade itself. The next three hours of trade saw the share under pressure and drift downwards to almost the Rs 50 level all over again. The share made an effort to rally thereafter but every rise saw an equally strong fall and this trend continued with the share giving up in the last half hour. The low of the day of Rs 49.50 on the BSE and Rs 49.30 on the NSE was made in the last half of trade. The share closed trading at Rs 49.95 on the BSE and Rs 50.05 on the NSE.

There are some lessons one needs to learn from the IPO of L&T Finance Holdings Limited. Withdrawal of forms after application is something which the system allows and it is a perfectly legitimate exercise. Even in this case, the HNI category which was initially subscribed 6.18 times reduced to 5.94 times post rejections and became less than half at 2.95 times when post allotment happened. This kind of withdrawal happens when investors believe that there would be no rewards for the investors and therefore withdraw their valid bids. It becomes imperative to price issues at prices which offer not only appreciation in the short to medium term but also ensure investors do not lose money. L&T Finance Holdings Limited was able to cash the goodwill of 61 years when it had priced its issue at a substantial premium to its listed peers. The response to the issue by retail investors and shareholders is testament to its goodwill and the poor response by QIB’s and final numbers by HNI’s indicate the over valuation or over pricing of the issue by the company. I believe this fine difference between the QIB’s and HNI’s who look at the quick return and the retail who looks at the long term track record and rewards loyalty should be looked into by more promoters looking to tap the capital markets in the near future.

The final word says that the issue has had a poor listing and there could be more pain going forward.

Subscribe to RSS Feed Follow me on Twitter!