
Timbor Home: Great Debut, Share closes at around day’s high. Gains 44%


Timbor Home Limited had a stellar debut at the bourses yesterday. The share listed at Rs 72 on both the BSE and NSE The high of the day was Rs 94.50 on the BSE and Rs 99 on the NSE. The open of Rs 72 was the low on both the BSE and the NSE. The share closed at Rs 91.20, a gain of Rs 28.20 or 44.76% on the BSE. The closing on the NSE was Rs 91.55, a gain of Rs 28.55 or 45.32%.

The company had issued shares in a price band of Rs 54-63 and the issue was overall subscribed 5.78 times. The retail portion did extremely well with the portion subscribed 14.22 times. The company is into the business of manufacturing and marketing modular kitchens.

Exchange Open High Low Close Net Change % Gain/loss Wt. Avg Volume Delivery Del %age
BSE 72.00 94.50 72.00 91.20 28.20 44.76 83.94 35433351 1505659 4.25
NSE 72.00 99.00 72.00 91.55 28.55 45.32 84.07 43714948 1789353 4.09
Total 79148299 3295012 4.16

The combined traded volume on the two exchanges was 791.48 lac shares which was 21.45 times the IPO size of 36.90 lac shares. The delivery volume was 32.95 lac shares or 4.16% of the traded volume and a staggering 89.30% of the IPO size. There appears to be some crazy interest built up into the share during the day’s trade and one is not sure about the reason for the same.

One financial television channel kept on flashing throughout the day that there were two block deals that were done on the counter and the size of the deal was 10 lac shares each. The source of the information certainly turned out incorrect and more importantly this assumption was wrong in the first place simply because the total issue was for 36.90 lac shares. The issue was oversubscribed in the HNI and retail category. The QIB portion was undersubscribed and all other shares other than the IPO issue were under compulsory lock-in. Very clearly the channel did not use logic to understand that what was being flashed is not possible even theoretically and they should have used caution before adding fuel to fire on listing day.
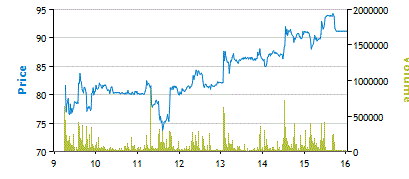
If one looks at the price chart one finds that the share after opening remained fairly steady in a broad band of Rs 77-83 right upto 11.15 am. The share took a sharp dip at that time and fell to Rs 74 and thereafter it has been a steady climb right through the day. The share closed virtually at the day’s high and had a great start to its innings at the bourses.

Retail investors have made good money in the share with the weighted average of the share being Rs 83.94 on the BSE and Rs 84.07 on the NSE. This clearly shows that all investors who have exited have made decent money and returns. The share closed with gains of about 45%.

On the buying side data and information available on the websites of the exchanges shows that there is one entity namely Albula Investment Fund Limited which has bought 1.5 lac shares on the NSE at an average price of Rs 91.80 while another fund Credo India Thematic Fund Limited has sold 91,688 shares at Rs 80.15. This data shows that there is no block deal either on the buy side or the sell side. One hopes that the regulators whether they are the exchanges or SEBI look into such issues as it is observed that many of these channels in their aim of being number one make statements or say incorrect things and misguide people.

Timbor Home: Great start. Share up 27% and holding well

Shares of Timbor Home Limited listed on the BSE and NSE today. The opening price of the share on the BSE was Rs 72, and it was an identical Rs 72 on the NSE as well. The high was Rs 84.70 on the BSE while it was Rs 99 on the NSE. The low was the open of Rs 72 on both the exchanges.

The company had tapped the capital markets with its issue for 36.90 lakh shares in a price band of Rs 54-63. The issue was open for subscription between the 30th of May and the 2nd of June. The issue received excellent support from the retail investors who subscribed their portion 14.22 times. The overall issue was subscribed 5.78 times.

Exchange  Open  High Low Close Net Change % Gain/loss Volume Wt. Avg
BSE 72.00 84.70 72.00 80.25 17.25 27.38 9818943 79.85
NSE 72.00 99.00 72.00 80.15 17.15 27.22 12234863 79.86
Total 22053806

After the first 100 minutes of trade, the share is holding very steady with gains of 27% at Rs 80.10 which is slightly above the average price of Rs 79.85. The share has seen excellent volumes so far with 220.53 lac shares traded which is almost 6 times the IPO size. So far so good is all one can say at this point of time. Investors particularly retail have made money in the issue and it appears that things have panned out well for them.

It would be interesting to see where the share closes and also the deliveries at the end of the day.

AVOID Rushil Decor IPO: Very small in size, Expensive

Rushil Decor Limited is tapping the capital markets with its IPO in a price band of Rs 63-72 for a net issue of 54 lac shares. The issue opens on Monday the 20th of June and closes on Thursday the 23rd of June.

Price Band  Rs 63 – Rs 72
Offer size in shares 56,43,750 Equity Shares 
Contibution by Promoters 2,43,750 Equity Shares
Net Offer in shares 54,00,000 Equity Shares
Issue Size Rs 34.02 crs at Rs 63 to Rs 38.88 crs at Rs 72
QIB’s 27,00,000 Equity Shares 
Non Institutional Investors 8,10,000 Equity Shares 
Retail Investors 18,90,000 Equity Shares 
Book Running Lead Manager Corporate Strategic Allianz Limited
Co-Book Running Lead Manager Indbank Merchant Banking Services Limited
Syndicate Member Hem Securities Limited
Issue Opening Date Monday 20th June
Issue  closing date  Thursday 23rd June
IPO Grade  ICRA grade 2/5  indicating below average fundamentals
Paid -up Capital Pre IPO 87,56,250 Equity Shares 
Paid -up Capital Post IPO 1,44,00,000 Equity Shares 
Market Cap post listing Rs 90.72 crs at lower band to Rs103.68 crs at higher band
Bid Lot 90 shares
Bidding Amount for Retail 2700 shares at Rs 72 or Rs 1,94,400 per application

Business
Rushil is into the business of manufacturing decorative laminated sheets and plain particle boards. The company has its manufacturing facilities in Gujarat. Its present installed capacity is 30 lac sheets of decorative laminate and 13,76,000 square metres of plain particle board. The company has a brand name “VIR” under which it markets its decorative laminate and board. The business is regulated and has huge entry barriers that require the grant of licenses for the manufacture of wood based products. The Supreme Court in 2002 had come down very heavily on this sector.
The company is a cost effective producer of laminate and particle board and has been operating at capacity and also producing higher than the installed capacity. The company has a well spread dealer network involving 70 distributors and 2150 dealers across the country. The company employs 51 sales executives and has 5 marketing offices.

Objects of the issue
The objects of the issue are as follows: –

Setting up of Medium Density Fibre Board plant in Karnataka Rs 7000.02 lacs
Margin for working capital requirement Rs.   336.84 lacs
Public issue expenses Rs      XX
General Corporate Purposes Rs      XX

The capacity of the MDF plant would be 90,000 cubic mts and the company has been sanctioned a term loan of Rs 44 crs by Bank of Baroda for the same.

Financials
The company has been in business since 1993. In 2005 two group companies Mica Rushil Pvt Limited and Rushil High Pressure Laminates were merged with the flagship company Rushil Decor.
The company had total income of Rs 102.63 crs in the year ended March 2010 and Rs 96.62 crs in the nine month period ended December 2010. The net profit after tax was Rs 3.85 crs in March 10 and Rs 3.76 crs in nine months ended December 2010.

Rupees in Lakhs year 2009 year 2010 9 months 
Dec-10
Domestic Sales 4070.04 4498.4 5296.92
Export Sales 4697.04 5047.83 3470.22
Total sales 8767.08 9546.23 8767.14
Other Income 793.22 624.41 605.29
increase/decrease in stock 119.32 92.03 290.14
Total Income 9679.62 10262.67 9662.57
Total Expenses 9225.85 9588.15 9141.44
Profit before tax 453.77 674.52 521.13
Taxes 176.24 289.13 145.22
Net Profit After Tax 277.53 385.39 375.91
NET MARGINS 2.87 3.76 3.89

The net margins seem to have improved in the current nine months and the significant change that has happened is the threefold increase in inventory from Rs 92.03 lacs in the year ended March 2010 to Rs 290.14 lacs in the nine month period ended December 2010. This has significantly helped the net margins improve from 2.87% in the previous year to 3.76% and now to 3.89%.

Comparisons
The company has chosen to compare itself with Century Ply and Greenply Industries. Century Ply Industries limited reported a topline of Rs 1,429 crs for the year ended March 2011 with a net profit of Rs 189.69 crs. The net margin is 13.27%. The other company is Greenply Industries which reported sales of Rs 1,231 crs and a net profit of Rs 25.09 crs. This drop in profit was on account of closure of one of its plants. The closure apart the company is significantly bigger in size of sales and is roughly 10 times the size of Rushil.
Centuryply is available at a PE multiple based on March 11 numbers of 7.72 times while Greenply is available at a multiple of just about 16.7 times.

Risks
The company is setting up the MDF plant using Chinese machinery which has not yet been very successful in India or has yet to prove its efficacy. The MDF board industry has not been very successful in the country because of various problems, and large players like Bajaj Hindustan have had problems in stabilising production. Availability of  raw materials has always been a concern and with environment issues in the case of felling of trees, this is a serious issue.

Valuations
Rushil Decor Limited is offering shares in a price band of Rs 63-72. The company earned a net profit of Rs 385.39 lacs in the year ended March 2010. The EPS based on the pre-IPO capital 0f 87.56 lac shares is Rs 4.40. If one were to consider the current year’s profit for the nine months on an annualised basis the same would be Rs 501.21 lacs. The fully diluted equity would be 144 lac shares and the fully diluted earnings per share would be Rs 3.48. Based on the IPO price of Rs 63-72, the price earnings multiple at which the shares are being offered would work out to 18.10 times at the lower end of the price band and 20.69 times at the upper end of the price band.  

Conclusion
This is yet another issue from Ahmedabad and the merchant banker is also from Ahmedabad. The pricing of the issue is not only expensive it is substantially higher than the market leaders with whom the company has chosen to compare itself. With nothing in it for investors why should one invest in a company is the moot question. It appears merchant bankers and promoters just do not understand that issues are to be priced at levels where investors who put their hard earned money make some money, not lose it. I believe one should simply avoid this issue and resist the temptation of there being “friendly” people behind the issue.

SEBI Disclaimer: – I do not intend to apply to the above issue 

Subscribe to RSS Feed Follow me on Twitter!