C.Mahendra Exports IPO: Issue subscribed

C.Mahendra Exports Limited which had launched its IPO for 1.5 cr shares in a price band of Rs 95-110 was oversubscribed 2.78 times. This IPO had created history by opening in 2010 and closing in 2011. The issue had opened on Friday the 31st of December 2010 and closed on Thursday the 6th of January 2011. The issue was subscribed in every category.

The details of the subscription level in various categories are given below: –

Category Shares Offered Shares Subscribed Times
QIB 7500000 7623480 1.02
NII 2259000 8819580 3.92
Retail 5250000 25295940 4.82
Overall 15000000 41739000 2.78

The retail portion was subscribed the highest at 4.82 times and has received substantially higher subscription than that of the QIB portion. In absolute terms while QIB’s bid for 76.23 lac shares, retail investors bid for 252.95 lac shares and the issue was effectively subscribed 1.68 times of the total by retail itself. This is a very high proportion and it would be interesting to see how the share performs on listing and also whether there are any withdrawals on final allotment of shares.

Heroes and Zeroes of the primary market in 2010

There were 70 IPO’s which included India’s first IDR issue from standard Chartered Bank, 6 FPO’s and 63 IPO’s. The table below gives a detailed picture of the performance of these issues. The details are in basically two segments where in the first segment the high, low, close and percent change in the listing week or first five days trade is given. In the second segment the high and low for the whole year and the close is given. The absolute change in Rs and the percent change are also given. In the middle there is an interesting column which talks of the percentage fall from high. This column captures the difference in percentage terms from the high to the close divided by the issue price as a percentage.
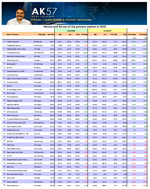
Click to view

Heroes & Zeroes Table

Coming to the Heroes of 2010, clearly the Hero was Jubilant Food works Limited which is the master franchisee of the pizza maker Dominoes in India, Sri Lanka and Nepal. The share which was issued at 145 has appreciated 330% to close at Rs 624.60.

The second hero was a little known Jewellery Company, Thangamayil Jewellery from down South headquartered in Madurai. This company had issued shares at Rs 75 which has appreciated to Rs 166.95, a gain of 122.6%. It becomes all the more creditable with two other jewellery players doing badly. Shree Ganesh Jewellery House from Kolkata which had issued shares at Rs 260 is down 23.94% at Rs 197.75 while Mumbai based Goenka Diamonds with an issue price of Rs 135, trading at Rs 76, down 43%.

The third hero was gymnasium services provider Talwalkar which issued shares at Rs 128 and have appreciated to Rs 269.85, up 110.82%.

Our hero numbers four and five are Gravita India which is up 102.68% and integrated textile player Mandhana Industries which is up 101.69%.

Coming to the zeroes of 2010, the pride of place is held by Aster Silicates which had issued shares at Rs 118. Within the first week of trade the high for the share was Rs 255.95 and the close at the end of the week was Rs 121.95. The low of the share for the year was Rs 29.50 and the close for the year Rs 36.30, a loss of 69.24%.

The second on the list is Tirupati Inks which issued shares at Rs 43 and within the first week itself the price had halved to Rs 25.15. The low for the share was Rs 10.90 and the share has closed at Rs 13.45, a net loss of 68.72%.

The third on the list is Emmbi Polyarns which against the issue price of Rs 45 lost 62.33% to close at Rs 16.95.

The other notable losers were CEBBCO and DB Realty.

A couple of high profile stocks were casualties this year. This included the like of SKS Microfinance which issued shares at Rs 985 and made a high of Rs 1490.70, and a low of Rs 559. The stock has lost close to Rs 930 from the high to the low. The entire fall has happened in a span of three months and one of the book running lead mangers even downgraded the stock to a sell with a price target of Rs 600. At the end of the year one of the expected high flyers of the year closed at Rs 643.85, down 34.63%.

Yet another high profile issue was the recent issue from A2Z Maintenance Services Limited. This was very well promoted  and coming from the stable of India’s Warren Buffet was expected to be a money spinner for all concerned. The share was issued at Rs 400 and even a great buying support on day one of over 35.62 lacs or 4.8% of the company’s equity post IPO by the promoter and the key investor was not enough to save the share from slipping 19% to close at Rs 323.

A quick summary of the 70 shares performance could be presented in the following manner.

1 share gains 330%

4 shares gain more than 100% but less than 125%

2 shares gain more than 75% but less than 100%

5 shares gain more than 25% but less than 50%

9 shares gain more than 10% but less than 25%

6 shares gain more than 5% but less than 10%

3 shares lost less than 5%

6 shares lost more than 5% but less than 10%

12 shares lost more than 10% but less than 25%

13 shares lost more than 25% but less than 50%

9 shares lost more than 50% but less than 75%

In all there were 27 shares that gained while 43 shares that lost. Clearly it has not been a good year as a whole for investors in the primary market and one expects that looking at this performance, promoters and merchant bankers will bring about better valuations going forward.

Let’s hope that the year 2011 where there is a very healthy pipeline of IPO’s planned has a better performance and more rewarding for investors. Investor returns is a key to the health of the market.

Wishing all readers a healthy and prosperous New Year 2011.

C.Mahendra Exports IPO: Avoid as sector has never rewarded investors

Issue offers little scope for appreciation

C.Mahendra Exports Limited is tapping the capital markets with an IPO which has opened on Friday the 31st December 2010 and will close on Thursday the 6th of January 2011. The issue is for 1.5 cr shares in a price band of Rs 95-105.

Price Band  Rs 95 – Rs 110 
Offer size in shares 1,50,00,000 Equity Shares
Issue Size Rs 142.5 crs – 165 crs
QIB’s 75,00,000 Equity Shares
Non Institutional Investors 22,50,000 Equity Shares
Retail Investors 52,50,000 Equity Shares
Marketcap Post Listing Rs 570 crs at lower band and Rs 660 crs at higher band
Book Running Lead Manager YES Bank Limited
Anand Rathi Advisors Limited
Isssue Opening Date Friday 31st December
Isssue  closing date  Thursday 6th January 
IPO Grade  ICRA grade 2/5 indicating below average fundamentals
Paid -up Capital Post IPO 6,00,00,000 Equity Shares
Bid Lot 60 shares
Bidding Amount for Retail 1800 shares at Rs 110 or Rs 1,98,000 per application

This is the only book-built issue one remembers that is spanning over two calendar years. There has been only one other case in 2006 but that was in the case of a fixed price issue. The issue from Cambridge Technology Enterprises Limited opened on the 29th of December 2006 and closed on the 9th of January 2007.

Business
C.Mahendra as a group is an integrated diamond and diamond jewellery player encompassing sourcing of rough diamonds, trading of rough and polished diamonds, processing of diamonds, and manufacture of diamond jewellery. The company carries out all these activities through a group of 11 companies which are owned 100% by the parent company. The company has four broad activities and they are carried out by these 12 companies which includes the parent company.
The five broad activities are as follows: – 1) Sourcing and trading in rough diamonds. 2) Cutting and polishing if diamonds. 3) Manufacture of diamond jewellery. 4) Marketing and trading in cut and polished diamonds. 5) Marketing of diamond jewellery.
The company has two diamond processing facilities at Udhna and at Varachha, both in Surat with an installed capacity of 2,40,000 carats per annum. The company has its jewellery manufacturing unit in Andheri (E) in Mumbai.
The company is proposing to expand its facilities by setting up a new diamond processing unit at Gujarat Hira Bourse, SEZ, in Surat and a jewellery manufacturing unit in Mumbai. Both these units are expected to commence production by September and October 2011 respectively. The company has 827 employees as of 30th June 2010. 
The company has marketing offices in Surat, Mumbai and New Delhi in India. Its international presence is in New York, Antwerp and Hong Kong. The company’s flagship brand is “CIEMME”. Currently the company sells it jewellery through 9 exclusive retail showrooms, one franchise and through shop-in-shop setups.
C.Mahendra is a sight holder of the Diamond Trading Company and is able to source rough diamonds directly from DTC and ALROSA. Besides these it also sources from Canadian, Russian and African mining companies.

Objects of the issue

1 Setting up of a diamond processing unit at Surat Rs 36.06 crs
2 Setting up of a jewellery manufacturing unit in Mumbai Rs 23.64 crs
3 Setting up of retail outlets Rs 30.00 crs
4 Finance Brand Development expenses Rs 20.00 crs
5 Investment in capital of C.Mahendra BVBA Rs 80.00 crs
6 General Corporate Purposes XX

Financials
C.Mahendra Exports Limited consolidated revenues of Rs 1,597.42 crs for the financial year ended March 2009 and Rs 1,865.29 crs for the year ended March 2010. In the first quarter ended June 2010, the revenue was Rs 677.44 crs. The net profit after tax for the period ended March 2009 was Rs 66.19 crs and a paltry Rs 5.97 crs for the year ended March 2010.The net profit for the first quarter ended June 2010 has improved dramatically and zoomed to Rs 40.38 crs. The company has reported an EPS of Rs 14.71 on the pre-IPO equity of 4.5 cr shares for the year ended March 2009; Rs 1.35 for the year ended March 2010 and Rs 8.96 for the first quarter ended June 2010.

Comparisons
The company has chosen to compare itself with three other companies namely Gitanjali Gems, Shrenuj & Company and Suashish Diamonds. The comparison matrix is by and large fair and puts C.Mahendra in fair light compared to its peers. Gitanjali is by and large the largest retail brand in the list and has consolidated sales of over Rs 6,500 crs for the year ended March 2010. As regards the other companies 2009-2010 has been a bad year for almost all diamond companies and things seem to be improving in the current year. Diamond business because of different countries, economic conditions and volatility in prices in a tough and low margin business has plenty of uncertainty. Its margins and profits are not easy to estimate as multiplying Q1into four and calculating profits for the year.

Risk factors
The biggest risk in this business is the volatile nature of rough diamond prices and the selling price of cut and polished diamonds. Diamond companies do well when economies do well and diamond companies make most money when global economies are doing well. This is a very capital intensive industry, having a very high working capital cycle. Total requirement of funds is high and though sales in rupee terms may be high, the absolute margins are fairly low. Being a high volume low margin industry, one wrong event can knock out the bottom line. There is a perception fear about the industry and people generally do not believe the balance sheets of companies in India involved in the diamond industry. This perception and the fact that diamond companies have in the past never been investor friendly makes this a neglected sector in the stock market and investors look to stay away from this sector. The last two issues from this sector namely Goenka Diamonds and Shree Ganesh Jewellery House have been mini disasters at the bourses. While Goenka Diamonds is trading at Rs 76.60 against an issue price of Rs 135, a loss of 43.26%, Shree Ganesh Jewellery House is trading at Rs 197.75 against an issue price of Rs 260, a loss of 24%. This was not considering the facy that the share made a low of Rs 107.10 and has recovered from there to the current prices. In recent times just one gem and jewellery company namely Thangamayil Jewellery has made money for investors. Its current share price is Rs 166.95 against an issue price of Rs 75 and the share is up over 122%.

Valuations
The share of C.Mahendra Exports limited is being offered at a price earnings multiple of between 6.46 times and 7.48 times its FY 09 earnings. If one were to ignore FY 2010 which was an aberration, based on Q1 ending June 2010, the earnings per share improves to Rs 6.72 for the quarter. On an annualised basis this would be a staggering Rs 26.88, but if we were to extrapolate on a conservative basis and expect the profit to be Rs 110 crs we would be talking of an EPS on a fully diluted basis post IPO to be Rs 18.33. Based on this expected earnings the share is being offered at a price earnings multiple of 5.18 times at the lower end and at 6 times at the upper end of the price band. On the offer price it does not leave much to appreciate simply because even assuming the profit to be roughly 2.75 times the Q1 profit, it leaves little for appreciation in the medium term.
The issue has opened for subscription on Friday and on the first day itself it has received bids for 48.18 lac shares which are 32% of the total shares offered of 150 lac shares. The issue getting subscribed may not be a concern and there may be some money made for the first hour flipper, but as history indicated this industry has not made money for the investor and there is nothing in this company which could change the trend.

Conclusion
The issue can be given the skip and many believe that well begun is half done. This issue is not the best way to start 2011. Avoid subscribing to the issue.

SEBI Disclaimer: – I do not intend to subscribe to the above issue.     

Subscribe to RSS Feed Follow me on Twitter!