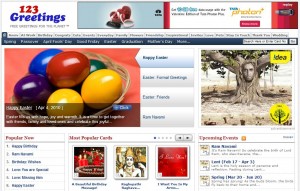
 Intrasoft technologies Limited (Intrasoft) is tapping the capital markets with an IPO which has opened on Tuesday the 23rd of March 2010 and closes on Friday the 26th of March 2010. The company is better known for its product 123 greetings, which is an electronic greeting cards website. The issue has a price band of Rs 137-145 and would raise between Rs 50-54 crs.
| Price Band |
Rs 137 – Rs 145 |
| Issue size in Rs |
Rs 50.69 crs to Rs 53.65 crs |
| Offer size in shares |
37,00,000 Equity Shares |
| QIB’s |
18,50,000 Equity Shares |
| Non Institutional Investors |
5,55,000 Equity Shares |
| Retail Investors |
12,95,000 Equity Shares |
| Post Issue Shares |
1,47,31,678 Equity Shares |
| Marketcap post issue |
Rs 201.82 crs to 213.61 crs |
| Book Running Lead Manager |
Collins Stewart Inga Private Limited |
|
Anand Rathi Advisors Limited |
| Isssue Opening Date |
Tuesday 23rd March |
| Isssue closing date |
Friday 26th March |
| IPO Grade |
3/5 by CARE indicating average fundamentals |
| Bidding Lot |
40 shares |
Business
In good old days, we all went to a shop, bought a card whether birthday, anniversary or what have you, actually filled up the same and then sent the card by hand delivery, courier or post. All this cost money and time. Now you go to a website, select a card and send it by e-mail to the person, and all this happens free to you the sender. Could this be a business model? Yes, there is no free lunch and the time that we are actually selecting a card, deciding on the matter and mailing it, advertisements pop up which are paid for by the advertiser and that is the business model.
Intrasoft is into this business. They have a library of 20,000 electronic greeting cards, which are rich in diverse multimedia content and are designed to cater to varying geographical and religious celebrations, occasions and other events. The website automatically refreshes itself every 15 minutes and incorporates a simple and user friendly interface which allows users to navigate through the library by occasion, popularity or text, customise them with rich content and music, and send them to any recipient email address at zero cost.
Intrasoft is India’s largest and the world’s second largest visited website in terms of unique visitors. The website attracted over 90 million unique visitors and this is growing at a very rapid rate. The company had a growth of 15% in the month of February 2010 as per comScore Media Metrix, a company which provides internet audience measurement services. In the electronic cards business the competitors are Evite.com and AG interactive. American greetings is yet another competitor but not strictly comparable because it is into other verticals as well.
Revenues are from advertisers and almost 90% of the total revenue derived by this company is from advertisements. Advertisers include major U.S. and Indian based organizations in the entertainment, retail, and information technology and internet space. The growth in revenues would come from customization and maximization of advertisement effectiveness which would result in significant increase in the billing rate. In 2007 the company was funded by Intel Capital.
The company has started 3rd party services for using the portal for online gifting. This at the moment is an insignificant portion of the revenues but has the potential to become a money spinner.
The current content is mostly in English and the new feature 123greetings Studio which is currently under test by a limited number of developers would be able to address this issue. This offering would allow the company to expand into new geographies and new user groups who would contribute to providing local content or new content in different languages. This would help grow the user base significantly.
Yet another feature being built in the software is the facility to send e-invitations for events and occasions. The introduction of this service would attract new user groups and also introduce the invitees who receive such invitations to the website.
Objects of the Issue
The objects of the issue include the following: –
| Branding and promotion |
Rs 2015.62 lakhs |
| Purchasing a corporate office at Kolkatta |
Rs 1300.00 lakhs |
| Investment in technology infrastructure |
Rs 200.00 lakhs |
| General corporate Purposes |
X |
Financials
The company has reported a net income of Rs 2017.86 lakhs for the year ended March 2008 and Rs 2335.15 lakhs for the year ended March 2009. The net revenue for the six months ended September 2009 is Rs 1050.33 lakhs. The net profit after tax for the year ended March 2008 is Rs 442 lakhs while for the year ended March 2009 is Rs 532.82 lakhs. In the six months ended September 2009 the profit is Rs 309.13 lakhs.
The business is highly cyclical and the second half of the year or October to March is typically more active. The reason is simple as almost the major festivals or occasions happen during this period. To illustrate the same Christmas, New Year, Chinese New Year, Diwali, Valentines’s day etc all happen in the second half of the year. Intrasoft has not given half yearly breakup of revenues but it would be safe to assume that around 1/3rd of the revenue comes in the first half and 2/3rd of the revenue comes in the second half of the year. Profit margins in this business are high and the net profit margins have been at 21.9% in March 2008 and at 22.8% in March 2009. They have improved significantly in the first half of the year ending March 2010 to a little over 29.4%.
Comparison
As mentioned earlier there is no competition or comparable company in India in this line or similar line of activity. Internationally there are comparables in the form of Evite.com and AG interactive. One can also look at American greetings and Hallmark. In the case of the last two they are strictly not comparable as they are into different verticals as well.
Valuations
The company cannot be compared on EPS and PE. The advertisement rates vary from the type of visitors and the ability to eliminate pop-ups which has made visitors shun a site. A website can attract higher ad rates simply by its ability to attract premium customers and its growth rate. The change in ad rates over a gradual curve can change from US $ 2.5-3 per 1000 to as much as 17-18$ per 1000. This of course cannot happen in a jiffy over time. Intrasoft is currently earning in the region of $ 4 per 1000.
Based on EPS the company earned Rs 3 on a fully diluted basis for the year ended March 2008, Rs 3.62 for March 2009 and Rs 2.10 for the half year ended September 2009. The growth potential, the marquee clients, the library size of 20,000 cards and the presence of Intel as an investor from 2007 are reasons good enough to bet on this company.
Risks
Any technology company always runs the risk of getting overtaken by new technology. Here such a risk does not remain because the habit of wishing, greeting and gifting cannot die or go away. The challenge is in introducing new products and innovation like the 123greeting studio and the e-invite add-ons which will help in establishing supremacy of the product. The 20000 strong library and additions to it will help in making this website a must see going forward. Complacency alone can kill the product otherwise the size of library ensures a head start and creates an entry barrier in itself.
Conclusion
I believe investment in Intrasoft will be profitable in the medium and long term. This is a company which offers an opportunity to multiply your money in time to come. It is not a story for mere listing gains. Subscribe for substantial gains in the medium and long term.
Sebi disclaimer: – I intend to subscribe to the above issue

 Goenka Diamonds and Jewels Limited had tapped the capital market with its IPO which opened on Tuesday the 23rd of March and closed on Friday the 26th of March. The issue was for 1 crore shares in a price band of Rs 135-145. The issue managed to get subscribed by 1.07 times.


