The week began with markets gaining strength and alternating between gains and losses till Wednesday when Thursday saw markets crack. BSESENSEX lost 759 points or Thursday and recovered almost all that on Friday gaining 732 points. NIFTY similarly lost 225 points and gained 237 points. The net change during the week saw BSESENSEX gain 356.59 points or 1.03% to close at 34,733.58 points, while NIFTY gained 156.05 points or 1.49% to close at 10,472.50 points. The daily closing change saw BSESENSEX gain 1,231 points and lose 934 points, for an effective weekly change of 2,225 points. Similarly on NIFTY it was a gain of 428.50 points and a loss of 272.45 points for a cumulative change of 700.95 points.
On a calendar year to date basis, BSESENSEX turned positive after Friday’s gains while NIFTY is marginally in the red. BSEMIDCAP and BSESMALLCAP are down 24.75% and 35.82% respectively, indicating the amount of pain and value erosion in the space. Even at these levels’ confidence is yet to return to the market place.
Dow Jones was under pressure and lost 1,107.06 points or 4.37% to close at 26,447.05 points. Dow on a calendar year to date basis is up 2.5%, having lost a lot of it during the week. The Indian Rupee saw recovery on Friday to gain 21 paisa or 0.29% for the week at Rs 73.56. During the week the rupee had touched a low of Rs 74.95.
In primary market news, the issue from Aavas Financers Limited listed on Monday the 8th of October and had a poor debut. Shares were issued at Rs 821 and after having a discovered price of Rs 758 closed for the day at Rs 773.15, a loss of Rs 47.85 or 5.83%. Delivery volume as compared to the IPO size at 3.74% was extremely low and this could be because the issue was undersubscribed in retail and HNI categories. The share at the end of the week recovered marginally to close at Rs 780.85, down 4.89%. What is significant is the fact that the anchor demand as circulated through a press release was for a billion dollars which was four times the issue size and in double digit for the anchor portion. Why such a ‘hot’ issue failed to get fully subscribed and more surprisingly trade at a discount in a week when markets were up, and recovering is a mystery. The only plausible answer is the battery of merchant bankers in their numerous international road shows were offered a higher price and based on the feedback they priced the issue which unfortunately is trading at a discount.
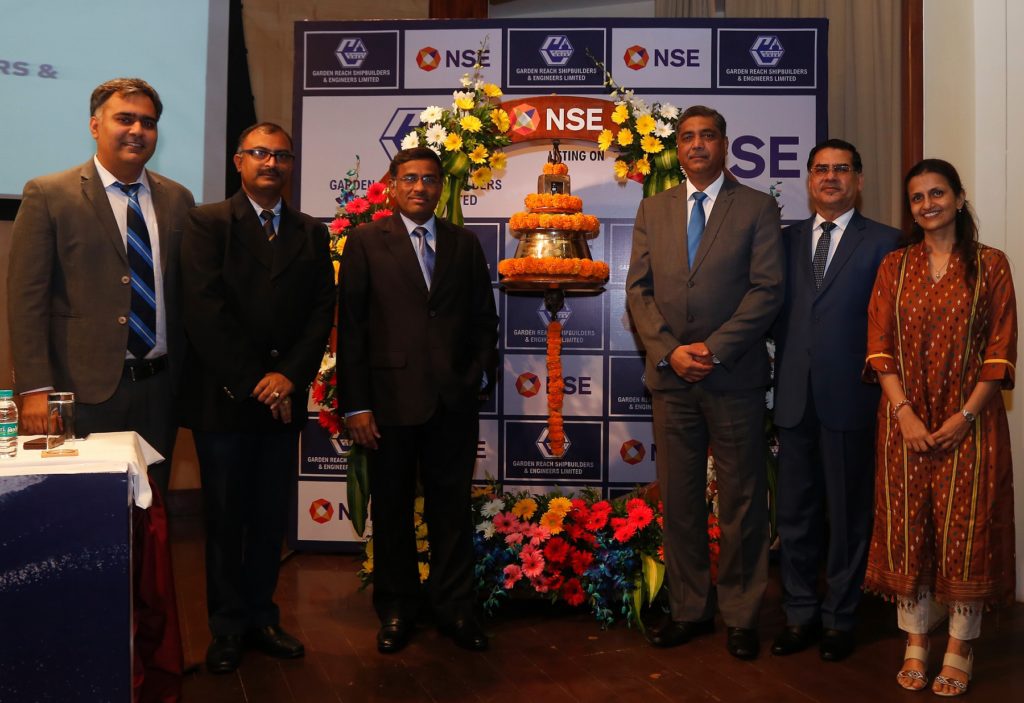
The other share to list was PSU Garden Reach Shipbuilders and Engineers Limited which had struggled to get subscribed. The issue was extended and just about managed to get subscribed. The issue had a discovered price of Rs 104 against an issue price of Rs 118. The share closed at Rs 105.90, a loss of Rs 12.90 or 10.93%. At week end the price had fallen to Rs 102.05, a loss of Rs 15.95 or 13.52%. Delivery volume was extremely low at under 1% of the issue size. One must remember that about 46 lac shares or 15.75% of the total 2.92 cr issue was from HNI’s, Retail and Employees. This effectively means that the share could remain under pressure for some time till deliveries from these investors is absorbed. With a market discount of close to 13-15% to the issue price of Rs 118, this share looks attractive when compared to the order book and the likely scale up that would happen in coming quarters.
The top gainers of the week were last week’s being losers, the oil marketing companies. HPCL which had lost a third in value, recovered during the week and gained Rs 53.20 or 24.38% to close at Rs 218.25. The sector under pressure was IT which has seen a sharp rally over the previous weeks. TCS posted a strong set of numbers but lost ground to lose 9.63% at Rs 1,918.40. The entire IT pack was down with BSE IT losing 7.03%.
Thursday is a trading holiday for markets because of Dussehra. Markets are likely to see squaring of positions when they have the holiday as global markets to are extremely volatile. Enough of a correction in terms of value and time seems to have happened and we are set for a rally in the coming days and weeks. Readers would recall that the heading of my last week’s article was “Market fall just about done – Look at small purchases”. Even though wee had a volatile market the BSESENSEX gained 1.03% for the week while NIFTY gained 1.49%. I continue with my positive outlook on the market and would recommend investors look to buy on dips and avoid shorting the markets.