
Aavas Financiers Limited – Share Closes 5.83% Lower On Listing Day

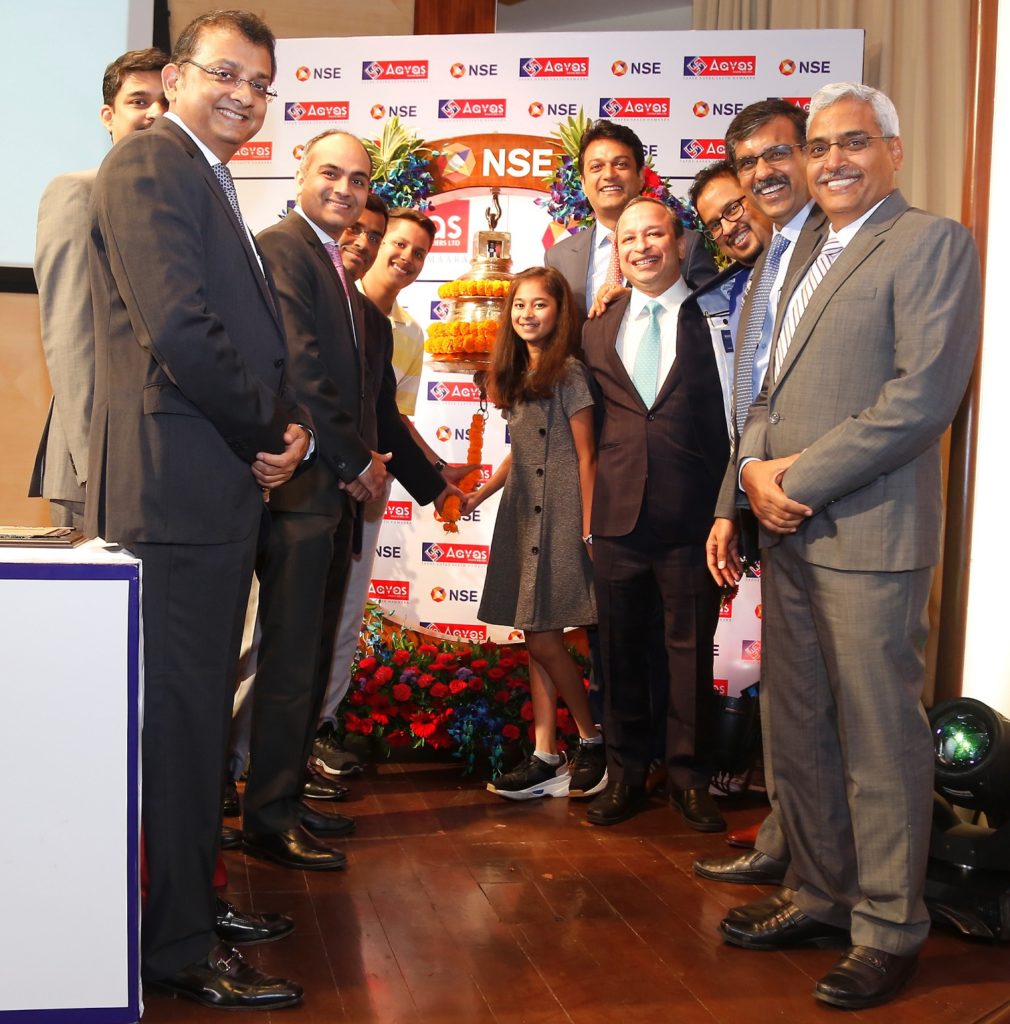
Shares of Aavas Financiers Limited listed on the bourses and had a poor debut day. The company had tapped the capital markets with its simultaneous offer for sale and fresh issue. The fresh issue was for Rs 400 crs while the offer for sale was for 1,62,49,359 equity shares in a price band of Rs 818-821. The issue had opened on Tuesday the 25th of September and closed on Thursday the 27th of September.
The company had earlier allotted 63,36,439 equity shares to 34 anchor investors comprising of 60 entities at Rs 1,821. The top allocation has been made to the erstwhile parent of the company A U Small Finance Bank Limited of 6,36,439 equity shares which corresponds to 10.04% of the total issue.

It was quite surprising that an issue which received such overwhelming support from anchor investors and saw its anchor book subscribed approximately 14 times as per press release issued by the company, was finally undersubscribed. Given that market conditions were trying, it still is difficult to digest.

The anchor demand was enough to subscribe the whole issue four times. Anyway that was history. The issue saw the total subscription at 0.97 times with QIB subscribed 2.77 times, HNI undersubscribed at 0.26 times and Retail undersubscribed at 0.25 times. There were over 87,000 applications received.

The discovered price on the BSE was Rs 758 and Rs 750 on NSE. This was a discount of Rs 63 on BSE and Rs 71 on NSE to the issue price of Rs 821. The high of the day was Rs 787.50 on BSE and Rs 787 on NSE. The lows were Rs 710 and 710.05 respectively.

Exchange Open High Low Close Net Change % Gain/ Loss Wt.Avg Volume Delivery Del %age
BSE 758.00 787.50 710.00 773.15 -47.85 -5.83 752.43 496064 71090 14.33
NSE 750.00 787.00 710.05 774.35 -46.65 -5.68 753.40 3534238 719030 20.34
Total 4030302 790120 19.60

The traded volume on the two exchanges combined was 40.30 lac shares. This was 19.08% of the IPO size and 27.26% of the non-anchor portion. Delivery volume was 7.90 lac shares which was 19.60% of traded volume. It was a mere 3.74% of the IPO size and 5.34% of the non-anchor portion. The total HNI and Retail applications were for about 26.70 lac shares and assuming the only people who sold today were these people we still have a long way to go with over 18.8 lac shares left.

The weighted average of the day’s trade was Rs 752.43 on BSE and Rs 753.40 on NSE. The closing price was Rs 773.15 on BSE, a loss of Rs 47.85 or 5.83% while on NSE it was Rs 774.35, a loss of Rs 46.65 or 5.68%.

The share has managed to survive today and considering market conditions, it could be said that the share has done reasonably well losing a mere 5.8%. If deliveries go up in the coming days and the share does not fall any further, it would have achieved its purpose.

For the battery of merchant bankers who were involved in this issue it would go down as yet another issue which closed below its issue price on listing day.
Market Fall Just About Done – Look at Small Purchases

Markets began on a strong note on Monday and that probably was one of the two good news last week. The other good news was that we had a holiday on Tuesday for the Father of the Nation’s birthday. Markets fell on the remaining three days and they were days of big falls. BSESENSEX lost 1,850.15 points or 5.38% to close at 34,376.99 points. NIFTY lost 614 points or 5.95% to close at 10,316.45 points. Broader markets saw the BSE100, BSE200 and BSE500 lose similarly between 5.50% to 5.72%.

Dow Jones was virtually flat losing a mere 11.26 points or 0.04% to close at 26,447.05 points. The Indian Rupee was under pressure and lost Rs 1.29 or 1.75% to close at Rs 73.77 to the US Dollar.

Friday saw RBI keep interest rates unchanged and this was contrary to what most people on the street thought. Consensus indicated a rate hike of 25 basis points but was held unchanged with a 5-1 vote in favour of unchanged rates. Markets tanked even after this surprise announcement because of what it understood about NBFC’s. Deputy Governor was highlighting the mismatch between short term borrowings with long term lending and the impact it had on ILFS while markets misunderstood the same and just hammered the entire NBFC sector.

Government reduced excise duty on petroleum products and has asked the OMC’s to bear a rupee of the Rs 2.50 price cut. While the market should have taken it positively and appreciated that finally something is being done on this front, they thought this is going back on the oil sector reforms and stocks from the OMC pack lost about a fourth to a third in value in just a mere two days. Downgrades in earnings have been announced and many brokerages believe there could be more cuts in prices which would have to be absorbed by the OMC’s.

Election dates have been announced for elections to five states starting from 12th of November to 7th of December. Chhattisgarh would have a two-phase poll on 12th and 20th November. Madhya Pradesh and Mizoram would go to polls on 28th of November and Telangana and Rajasthan would have polls on 7th December. Counting and results would be declared on Tuesday the 11th of December. While opinion polls would start emerging, market would form a view closer to polling and observe how the campaign proceeds. One is not sure whether the present opposition would be able to present a united front against the ruling BJP or not.

In primary market news, the issue from Aavas Financers Limited would list on Monday followed by the one from Garden Reach Ship Builders and Engineers Limited. Both issues are expected to list below their issue price. In the case of Aavas Financers it would be interesting to see who the sellers on day one is, as the retail and HNI participation was a mere 0.26 and 0.25 of the issue. The bulk of the subscription was by QIB’s who had subscribed their portion 2.77 times. The overall issue was just about subscribed at 0.97 times.

The current meltdown has claimed its first victim in the form of Dinesh Engineers Limited which had tapped the capital markets with its primary issue of I crore shares in a price band of Rs 183-185. The issue was open from Friday the 28th of September to Wednesday the 3rd of October. The issue did not receive a single bid from QIB’s and saw subscription of 0.30 and 0.10 from HNI’s and Retail respectively. The overall issue was subscribed 0.08 times and was withdrawn blaming poor market conditions. One wonders what the need was to open the issue in these conditions. It could easily have done so with June audited results and opened a fortnight later.

Markets have lost 4,000 points on the BSESENSEX and 1,270 points on NIFTY in the last four weeks. It’s a steep correction and has broken the back of the markets. There have been various factors which contributed to the same including valuations, rising crude oil prices and depreciating rupee. The ongoing trade war contributed to it as well. If this was not enough, a chain reaction with falling prices led to margin calls and liquidation of positions which led to further selling pressure.

Is this the end of the markets or the beginning of uncertainty? I believe markets will get to consolidate shortly and we should see reasonable valuations bringing back investors to the market. Hold your horses and do selective buying only. Avoid shorts at any cost.

Dinesh Engineers Limited – Issue Withdrawn

Dinesh Engineers Limited had tapped the capital markets with its fresh issue of 1 cr shares in a price band of Rs 183-185. The issue was open between Friday the 28th of September and Wednesday the 3rd of October. The company had kept the option to have anchor investors, but on the day chosen for the same, decided to opt out of it. Considering that markets were in a bad shape one wonders why the issue was opened in the first place.

This issue was lead-managed by Hem Securities Limited. This was probably their first issue on the main board, or to be on the safer side, an issue on the main board from them after a very long time. Hem Securities has been doing very well in the SME segment and is one amongst the top three merchant bankers in this segment.

The company chose to open its issue on the last day of the half year as their document had financial numbers for the year ended March 2018. To choose not to provide audited numbers for the later period say June 2018, they took a monumental risk with the issue considering market conditions where the BSESENSEX has lost 4.000 points in a span of four weeks. The outcome could only be one – Suicidal and that is exactly what happened. The issue bombed big time.

QIB portion which is mandatory for any issue received no bids. 50 lac shares had to be subscribed in this category and there was no bid. No spill over from other segments is allowed into the shortage if any of QIB subscription. Why the banker chose to open the issue in the first place is a mystery to me and the market as well. The response from the other two segments was no different. There were bids for a mere 4.54 lac shares in the HNI category against a bucket size of 15 lac shares. Retail was even worse with bids for 3.51 lakh shares against a bucket size of 35 lacs. The final tally was 8.06 lakh shares for an IPO of 100 lakh shares.

Company informed the exchange that the issue stood withdrawn. They stated that “looking at the volatile market conditions and prevailing market sentiment on the IPO, the comp-any in consultation with the BRLM has decided to withdraw the IPO.

This hasty decision of launching the IPO would cost the company dearly in terms of existing business as well. This is a setback for the company, the merchant banker and the primary markets. Coming as it did after a couple of issues which struggled and with one of them having to extend the closing date, this was probably the last straw on the camel’s back. One wonders whether what happened could have been avoided.

Subscribe to RSS Feed Follow me on Twitter!