
| Name | Date of listing | Issue Price | closing price | closing price | % gain loss | change over |
| 25th Mar | 18th Mar | over week | lssue price | |||
| Acropetal Technologies | 10th March | 90 | 70.1 | 120.45 | -41.80 | -22.11 |
| Sudar Garments | 11th March | 77.00 | 114.20 | 93.70 | 21.88 | 48.31 |
| Fineotex Chemicals | 11th March | 72.00 | 215.30 | 169.80 | 26.80 | 199.03 |
| Lovable Lingerie | 24th March | 205.00 | 250.75 | N A | 22.32 | 22.32 |
Performance of Newly Listed Shares 25th March 2011
March 27th, 2011
Comments Off on Performance of Newly Listed Shares 25th March 2011
Lovable Lingerie IPO: Shares of to a good start
March 25th, 2011
Comments Off on Lovable Lingerie IPO: Shares of to a good start
Selling pressure sees gains reduce to about 22%
Lovable Lingerie Limited listed yesterday at the BSE and NSE. The opening price at the BSE was Rs 261.50 and at the NSE was Rs 240. The high of the day which was made in the first fifteen minutes of trade was Rs 278.95 on the BSE and an almost similar Rs 278.90 on the NSE. The low on the BSE was Rs 241.40 and was made late in the afternoon. The low on the NSE was the open of Rs 240 itself. The share closed for the day at Rs 249.20 on the BSE, a gain of Rs 44.20 or 21.56%. On the NSE the closing price was Rs 249.55, a gain of Rs 44.55 or 21.73%.
| Exchange | Open | High | Low | Close | Net Change | % gain | Wt Avg | Volume | Delivery | Del % age |
| BSE | 261.50 | 278.95 | 241.40 | 249.20 | 44.20 | 21.56 | 259.17 | 17267081 | 815885 | 4.73 |
| NSE | 240.00 | 278.90 | 240.00 | 249.55 | 44.55 | 21.73 | 259.17 | 23297573 | 1931207 | 8.29 |
| Total | 40564654 | 2747092 | 6.77 |
Lovable Lingerie had launched its IPO for 45.5 lac shares in a price band of Rs 195-205. The issue was very well received and was subscribed a staggering 35.21 times. The HNI portion was subscribed almost a hundred times at 99.87 times. This made the leveraged HNI cost of finance almost Rs 76. The issue was priced at the upper end of the price band of Rs 205, which meant the price and the cost of interest was not visible for the HNI investor.
The selling price of this issue was the substantial discount in valuations that this share was being offered at compared with Page Industries which is the manufacturer of the “Jockey” brand in India. There sales are expected to cross the Rs 500 cr mark while Lovable would in all likelihood finish March 2011 with sales of just about Rs 115 crs. One must also remember that the brand “Lovable” has been around for about 17 years. In any case with the price having risen roughly 22% on day one of listing, that attraction also disappears. The company is raising Rs 90 crs through this issue and in terms of capacity increase roughly one fourth of the amount raised would be used for the same.
The company had allocated shares to anchor investors and effectively the size of issue which could be delivered gets reduced by the same amount. The effective size of the IPO from 45.5 lakh shares becomes 38,67,500 shares.
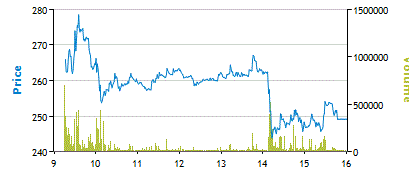 There was BRISK trading witnessed in the share throughout the day. The total traded volume was 405.64 lakh shares which was 8.91 times the IPO size. In terms of delivery the number of shares marked for delivery was 27.47 lakh shares which were 6.77% of the trading volume and 60.37% of the IPO size. If one were to deduct the shares allotted to anchor investors which are locked in for one month and therefore not good for delivery, this percentage increases to 71.03%. Coming to the pattern of trading during the day there are two distinct phases where the share has fallen sharply with volume. The first phase was in the morning around 9.45 am when the share fell from its high of about Rs 280 to Rs 255. Over the next four hours the share price improved gradually to Rs 267 and then again there was a sharp fall which took the price down to the low of the day of Rs 241.40. The share then recovered to close at just about Rs 249-250.
The share has had a good beginning and now needs to start delivering on the financial performance for the market interest to sustain. These days’ small issues come with ‘outside support’ and that keeps the interest alive. It must be pointed out that though everybody and in particular the promoters like the share price to be high, it all comes at a cost which is borne by the company and nobody else. Investors should keep this in mind when trading in such shares. At the end of the day it is the investor who provides the fodder for the cannons.
In conclusion a good performance with the share gaining 21.5% at the end of the day and being under selling pressure in the latter half of the day.
SBI Bonds: Series 3 and Series 4 listing day
March 24th, 2011
Comments Off on SBI Bonds: Series 3 and Series 4 listing day
Bonds close day with gains of 2.67%
SBI Bonds which were issued in the last week of February were listed today. Since writing the article another corporate action has happened. The company announced the record date as the 17th of March for payment of interest for the year ended 31st March 2011. What this effectively means that even if one were to sell the bond today or till the 31st March, the Interest at the coupon rate for the 15 day period from the date of allotment to the end of the financial year ending 31st March 2011 would accrue to the original applicant. If we were to assume that the person had applied for the 9.95% bond than the accrued interest would roughly be Rs 41 per bond. The flip side to this is that the buyer of the bond loses interest on his investment even though he has paid for it. The bond prices are likely to remain firm as long as the coupon rate is the highest as bonds trade on yield basis.
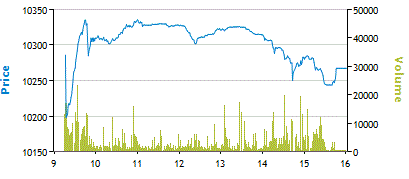 The bonds closed for trading at a price of Rs 10,267. This is an effective premium of Rs 267 per bond. IF one adds the interest on the application amount of about Rs 55, the incentive which was given to brokers and passed on to applicants of about Rs 75 per bond, the total return in about 1 month to investors is Rs 437 per bond. (Rs 267 premium, Rs 40 accrued interest, Rs 55 interest on application and Rs 75 as incentive).
The yield on the 9.95% bond at the present market price of Rs 10,267 works out to 9.69%. There is no accrued interest and once the bond has traded for a few weeks one would find the yields increasing as there would be an interest component in the price as well.
The yield factor can be further confirmed from the price of the 10 year maturity bond issued to retail investors at a coupon rate of 9.75%. This bond is trading at a nominal discount and closed the day at a price of Rs 9,970. This price makes the yield at 9.78%. If one were to look at the bonds issued for QIB’s and HNI’s, the price for the 10 year maturity bond with a coupon rate of 9.3% was trading at Rs 9,905 which corresponds to a yield of 9.38% while the 15 year bond with a coupon rate of 9.45% was trading at a price of Rs 9,919 or a yield of 9.52%.
The difference in yield is varying from the lowest at 9.39 for the 10 year 9.30% bond to the highest of 9.78% for the 10 year 9.75% bond. The yields would have to converge and they would become much closer than what they are in the next week or two. One should also remember that this was the first big bond issue where there has been such a large retail participation. The knowledge of retail and even the intermediaries whom they interact with is not upto the mark and hence there was so much of confusion as to what to expect from the issue and which bond to apply for?
I believe this is a good beginning and in the coming year 2011-12 bond offerings would increase in number in a substantial manner and would offer trading and investment opportunities for investors.
The returns of Rs 437 per bond works out to almost 4.37% per month and it would be a substantial gain for retail investors.

